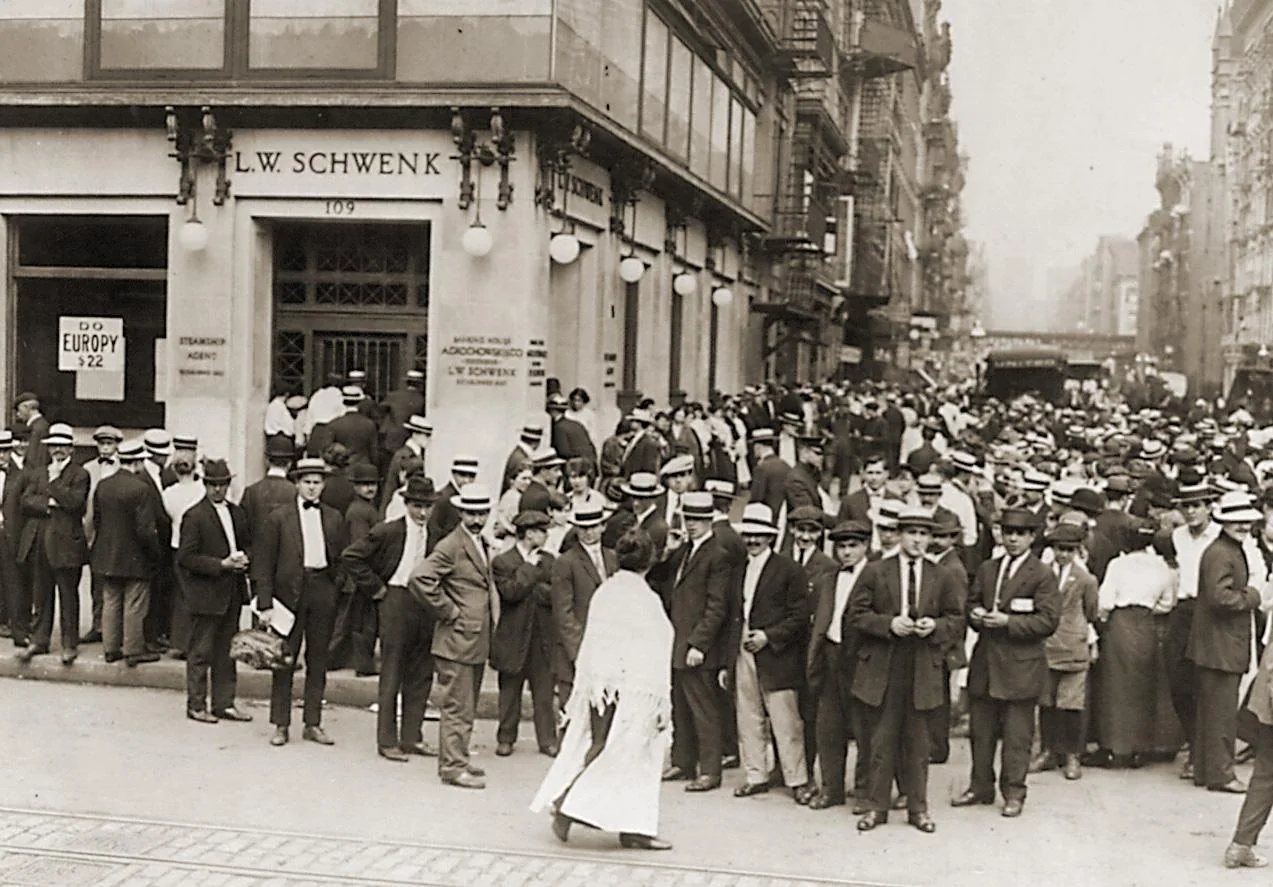
A bank can be perfectly healthy in the morning and gone by the end of the week. The reason is the bank run, a rush by depositors to withdraw their money all at once. Runs are driven by fear rather than arithmetic, and they have brought down banks for as long as banks have existed.
Why Banks Are Vulnerable
Banks do not keep customers’ deposits in a vault. They lend most of the money out as mortgages and business loans or invest it in bonds, keeping only a fraction available as cash. This system, called fractional reserve banking, is what allows banks to pay interest and finance the economy. It also creates a mismatch. Deposits can be withdrawn at any moment, while loans are repaid over years. On an ordinary day only a small share of customers want their money, so the system works. If everyone asks at once, no bank can pay.
How a Run Unfolds
A run usually starts with a doubt: a rumor of losses, a falling share price, a troubling news report. Some depositors withdraw their money to be safe. Others see them leaving and follow, since those who arrive last may get nothing. The fear fulfills itself. To raise cash, the bank must sell assets quickly, often at a loss, which weakens it further and gives more depositors a reason to leave. A bank that could have survived is destroyed by the belief that it would not.
From the 1930s to the Smartphone
During the Great Depression, thousands of American banks failed as panicked customers lined up outside their doors. In response, Congress created the Federal Deposit Insurance Corporation in 1933. The FDIC guarantees deposits, today up to $250,000 per depositor at each bank, so most customers have no reason to run. Insurance did not end the problem. In March 2023, customers of Silicon Valley Bank, many of them companies with balances far above the insured limit, tried to pull out about $42 billion in a single day using their phones and computers. The bank was closed by regulators the next day. Runs that once took weeks now take hours.
How Runs Are Prevented
Deposit insurance is the first line of defense. The second is the central bank, which acts as a lender of last resort, lending cash to sound banks that are short of it so they do not have to sell assets at fire-sale prices. Regulators also require banks to hold capital to absorb losses and enough liquid assets to meet sudden withdrawals. When a bank does fail, authorities often arrange a quick sale to a stronger bank so that customers keep access to their accounts.
Conclusion
Bank runs reveal that banking rests on confidence. A bank is safe as long as its depositors believe it is safe, and that belief can change quickly. The safeguards built since the 1930s have made runs rare and far less damaging for ordinary savers. They have not eliminated the underlying weakness, which is why the stability of banks remains a constant concern for regulators.